Home › Coverages › Dental Lab Insurance
Insurance for dental laboratories
Dental lab insurance centers on what leaves your bench: crowns, bridges, dentures and appliances that a patient wears long after the case ships. Most labs need products-completed operations liability, property and breakdown coverage for milling and furnace equipment, commercial auto for delivery routes and workers' comp for technicians.
- Since 2003
- 12+ A-rated carriers
- 28 states
- Independent agents
Start your dental lab insurance quote
Takes about two minutes. A licensed agent follows up.
Licensed in 28 states · NPN 7642818 · Since 2003
Dental lab insurance from the underwriter's side of the bench
A dental lab is a manufacturer. It makes crowns, bridges, dentures, night guards and implant restorations to a dentist's prescription and ships them back out. Underwriters treat it that way. Dental labs are classified on their own for general liability, separate from dental offices, and have their own workers' comp class in most states.
Expect questions about your annual revenue and what you make, the materials you use, how many technicians and drivers you employ, the value of your equipment, your building and whether you do anything beyond fabrication. Many labs qualify for a business owner's policy with standard carriers, though eligibility depends on the carrier, the building, revenue and property values per location, and claims history.
How claims tend to reach a lab
- Through the dentist. A patient's claim usually starts with the treating dentist. The lab can be brought in over the appliance itself, and working to a prescription doesn't remove the lab's exposure for what it made.
- Through the product. Bodily injury from a defective appliance after it leaves the lab, such as a fractured restoration that's swallowed or inhaled, or a reaction to a material, falls under the products-completed operations hazard.
- Through the shop floor. Cuts, burns from furnaces, dust and chemical exposure, and repetitive strain from fine handwork.
- Through the road. Pickup and delivery routes put drivers, vans and personal cars into the picture.
Example scenario: A three-unit bridge leaves the lab on a Tuesday and is seated the following week. Seven months later a connector fractures, the patient swallows a fragment and spends a night in the emergency room. The patient sues the dentist, and the dentist's attorney brings the lab in over the bridge's design and material. Products-completed operations coverage is the part of the lab's liability policy written for that kind of claim, subject to its wording and its own aggregate limit.
The coverage stack for a dental laboratory
Labs share some building blocks with dental offices, but the weight sits in different places: the product, the machines and the vehicles.
General liability with products-completed operations
Injury or damage caused by what you make after it leaves the lab, plus everyday premises claims from visitors and couriers. General liability insurance
Property and equipment
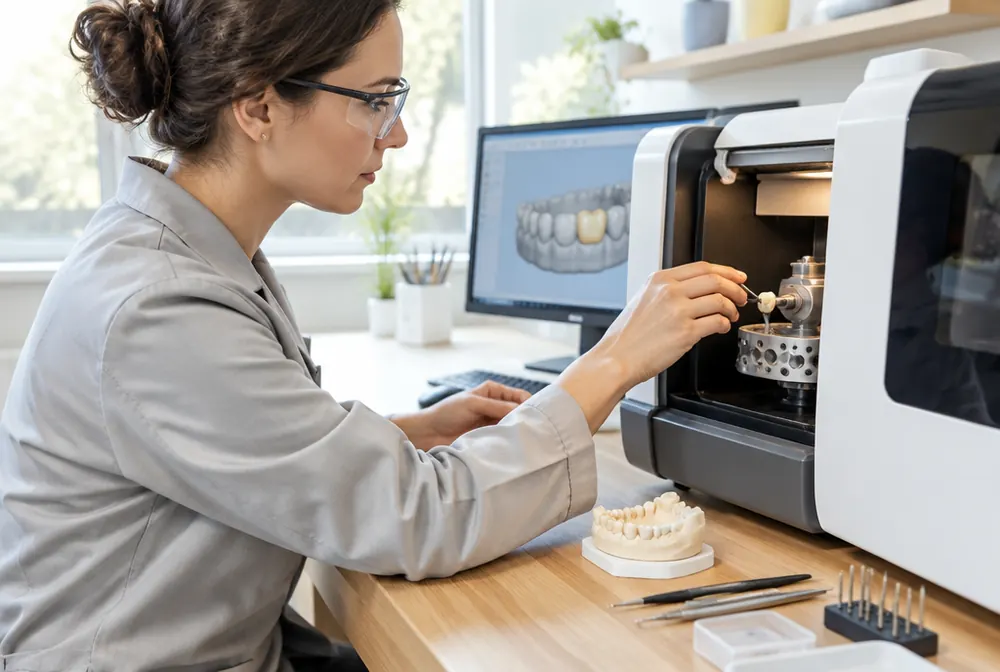
Mills, sintering and porcelain furnaces, 3D printers, scanners and CAD/CAM workstations at replacement cost, with equipment breakdown. Property and equipment insurance
A business owner's policy
Property, liability and business income in one policy for a lab that fits the carrier's size and building rules. Business owner's policy
Business income
Lost income and payroll while covered damage keeps the lab from producing, plus extra expense to send cases out or rent space. Business income coverage
Commercial auto and hired or non-owned auto
Coverage for lab-owned delivery vans, and for the lab's liability when staff run cases in their own cars. An umbrella can sit above it. Umbrella insurance
Workers' comp for technicians
Cuts, burns, dust and repetitive strain, rated under the state's dental laboratory class. Workers' comp
Cyber
Digital impressions, prescriptions and dentist portals all carry patient details and keep the lab running. Cyber insurance
Where lab coverage gets misunderstood
What dentists, landlords and lenders ask of a lab
Your clients, your landlord and your lenders each have a stake in how the lab is insured.
- Dentist clients and dental groups. Larger accounts may ask for a certificate showing general liability with products-completed operations, and sometimes for additional insured status. Read the account agreement before you sign it.
- Landlords. Labs often lease flex or light-industrial space with ventilation, dust collection and electrical work for furnaces and mills. That build-out is usually yours to insure. Expect additional insured and waiver of subrogation requests.
- Equipment lenders and lessors. Loss payee status on the machines they finance.
- Your state's comp system. In most states, technicians are rated under class 4692, Dental Laboratory. As one example, Indiana's advisory rate effective January 1, 2026 is $0.339 per $100 of payroll, with a $267 minimum premium, before your experience mod and carrier pricing. Pennsylvania uses its own class, 0489, Dental Laboratory Pennsylvania lab classes, and California classifies the manufacture or customization of dental products primarily for others as 4692, Dental Laboratories California lab rules. Ohio labs get comp only from the state fund, plus stop-gap employer's liability from a private carrier Ohio's comp system.
Growing a dental lab
Labs grow by adding machines, people, routes and bigger accounts. Each one changes the program.
- A new mill, printer or furnace. Add it to the equipment schedule the week it arrives, and confirm breakdown coverage applies.
- More technicians. Workers' comp is priced on payroll, so a bigger team means a bigger audit at year end. Estimate payroll honestly up front.
- New routes or vans. Every new vehicle and regular driver should be reported to your auto carrier.
- A large group account. More volume to one client often means higher liability limits, a request for an umbrella and certificates on short notice.
- A second location or a merger. Both sites on one schedule, with property values and business income for each.
Our licensed team starts with your equipment list, your driver setup and your largest client agreements, then compares options for the lab.
Questions lab owners ask
Is a dental lab liable if a crown made to a dentist's prescription fails?
Does general liability pay to remake a crown?
What workers' comp class code does a dental lab use?
Do we need commercial auto if technicians deliver cases in their own cars?
Is a milling machine covered if it just breaks?
Keep reading
Ready to see what you'd pay?
Independent agents, 12+ A-rated carriers, and a licensed agent back to you within one business day.